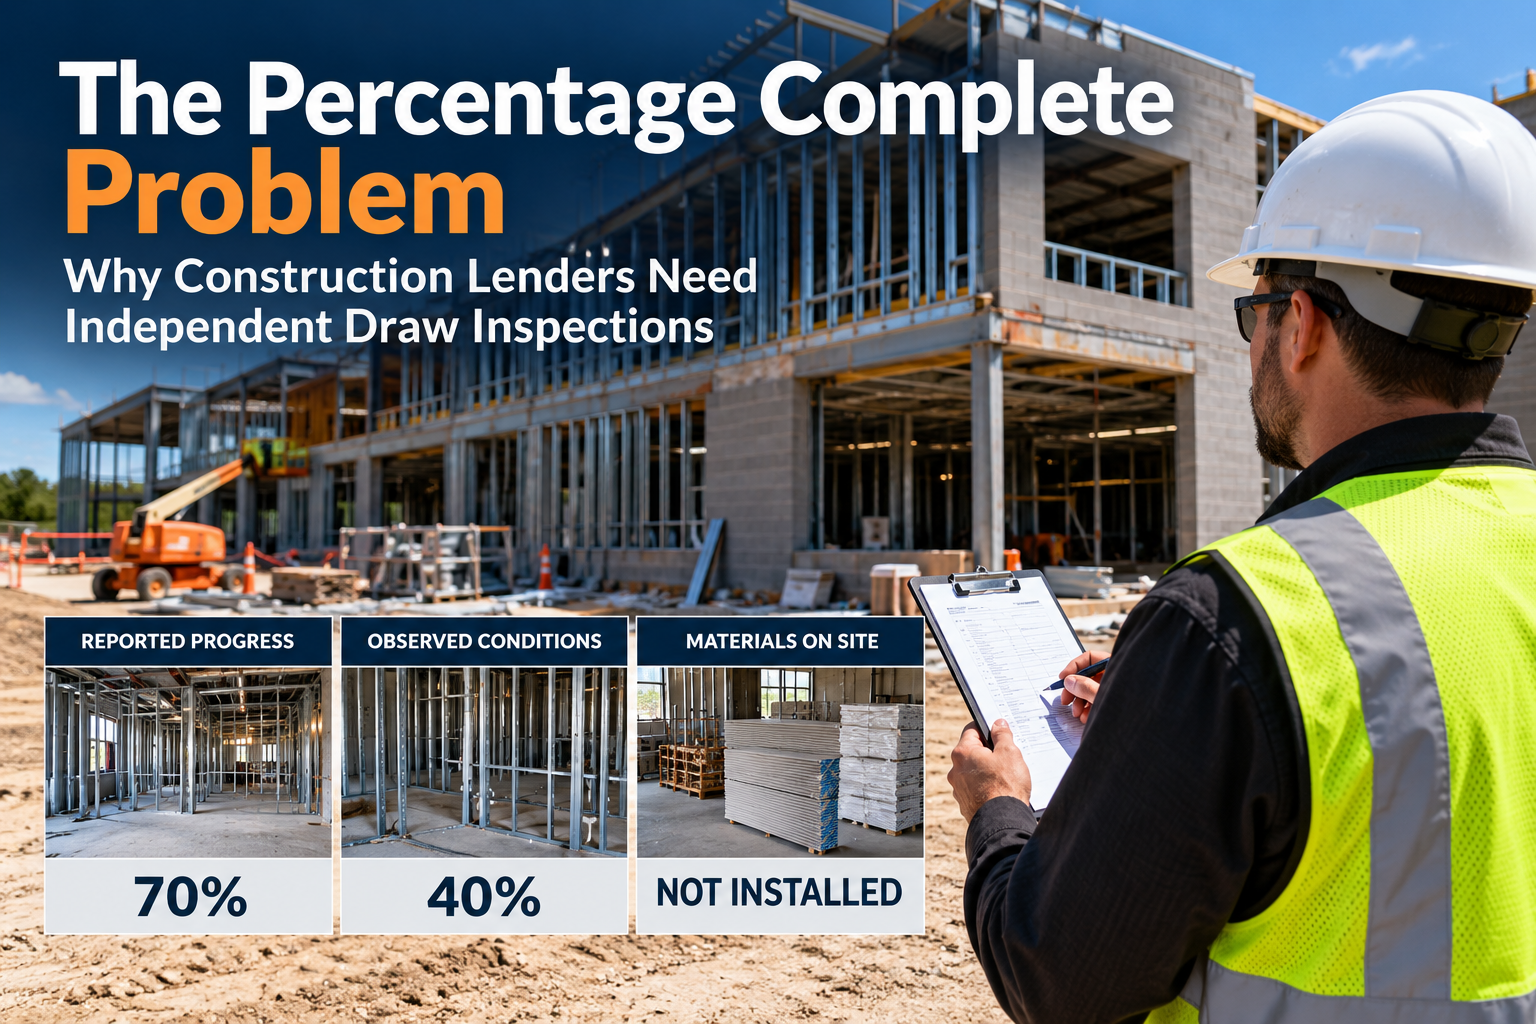
A contractor submits a draw request stating that the electrical work is 70% complete, HVAC is 65% complete, and interior finishes are 50% complete.
But what exactly does 70% complete look like?
More importantly, how does a lender know that the amount of money being requested reasonably corresponds with the work actually in place at the project?
That is one of the central purposes of a Construction Loan Draw Inspection.
Construction lenders release funds incrementally as work progresses rather than funding an entire project upfront. Before approving each subsequent draw, the lender needs reliable information about the observable status of construction.
On projects across South Jersey, the Route 1 corridor, and the Philadelphia suburbs, we routinely see draw requests where the reported numbers and the conditions in the field tell two different stories. Usually the gap is honest optimism. Occasionally it is not. Either way, the lender is the party advancing the money.
An independent draw inspection provides another set of eyes on the project. It documents visible progress and helps the lender identify situations where reported completion and observed site conditions may not align.
For lenders, the inspection is not simply about confirming that construction is occurring. It is about protecting the relationship between money advanced and work completed.
A Contractor’s Percentage Complete Is Not a Verified Percentage
Contractors and developers routinely track construction using percentages of completion. On most commercial projects, those percentages appear on the AIA G702 Application and Certificate for Payment and its G703 Continuation Sheet, which break the contract sum into line items from the schedule of values.
The challenge is that percentages can be subjective.
Consider a commercial renovation where a contractor reports:
- Electrical: 70% complete
- Plumbing: 75% complete
- HVAC: 60% complete
- Fire suppression: 50% complete
- Interior finishes: 40% complete
Those numbers may be reasonable. But without observing the project, the lender has limited ability to understand what they represent in the field.
Electrical rough wiring may be substantially installed while panels, fixtures, devices, terminations, testing, and final connections remain incomplete. HVAC ductwork may be largely installed while rooftop equipment, controls, electrical connections, balancing, startup, and commissioning remain outstanding.
A reported percentage needs context. A construction loan draw inspection provides it.
What an Independent Draw Inspector Actually Evaluates
A construction draw inspector does not simply walk the building and confirm that workers are present. The inspection should document observable progress across each major construction component applicable to the project.
Depending on the scope, this may include:
- Site improvements and utilities
- Foundations
- Structural framing
- Roofing
- Exterior walls and building envelope
- Windows and glazing
- Plumbing
- Electrical systems
- HVAC systems
- Fire protection
- Elevators
- Insulation and drywall
- Interior finishes
- Fixtures and equipment
- Exterior improvements
- Remaining work
Photographs accompany the observations so the lender has a visual record of conditions at the time of inspection. When previous inspection reports are available, each subsequent visit adds to a chronological record of construction progress, which is particularly valuable on projects with monthly draws.
Why Percentage Complete Is Difficult to Determine
Construction rarely progresses evenly. One trade may be well ahead while another waits on materials. Some areas of a building may be nearly finished while others remain at rough-in.
There is also a significant difference between something being installed and something being complete. Consider a rooftop HVAC unit. The equipment may be sitting on the curb, but several items could remain:
- Electrical connections
- Gas connections
- Condensate piping
- Controls
- Duct connections
- Startup
- Testing and balancing
- Commissioning
Calling the HVAC system complete because the equipment has been set would give the lender an incomplete picture.
On a recent mixed-use draw in Burlington County, the pay application carried HVAC at 80%. Both rooftop units were set, but neither was wired, piped, or started, and no ductwork had been connected at the curbs. The equipment was on site; the system was not close to 80% complete.
The same principle applies throughout construction:
- Drywall may be hung but not finished.
- Electrical wiring may be installed but not terminated.
- Plumbing fixtures may be present but not connected.
- An elevator may have major components installed while commissioning and state approvals remain outstanding.
Progress should be evaluated on observable installed work and remaining scope, not on the presence of materials or equipment.
Installed Materials Are Not the Same as Stored Materials
A draw inspection should distinguish between materials incorporated into the building and materials that are merely present at the site.
A project might hold pallets of flooring, plumbing fixtures, switchgear, HVAC components, doors, cabinetry, or other materials awaiting installation. Those materials may represent legitimate project value, but they are not completed construction.
Depending on the lender’s requirements, stored materials may need to be separately identified, photographed, and documented. Lenders often pair the field observation with invoices, bills of sale, and evidence of insurance, which the lender or title company reviews.
This distinction matters most when large quantities of high-value equipment arrive before installation. The lender needs to understand what has been installed, what is stored, and what remains outstanding.
Balance to Complete: The Question Behind Every Draw
The percentage complete on a single line item matters. The bigger question for most lenders is whether the loan remains in balance, meaning the undisbursed funds are sufficient to finish the remaining work.
If a project reports 75% complete overall but the field shows roughly 55%, the lender may have advanced money ahead of the work. The remaining budget may then be too thin to carry the project to completion.
An independent observation of remaining scope gives the lender a field-based check on that balance. It also helps when change orders shift costs between line items, or when retainage is being held against work that is not yet in place.
Lien waivers, title updates, and change order approvals remain the lender’s and title company’s paperwork. The draw inspection supplies the field side of the picture.
Draw Inspections Can Identify More Than Progress
A construction progress inspection can also reveal conditions that warrant additional attention, such as:
- Work appearing materially behind the reported schedule
- Major building systems not yet installed
- Previously observed work showing little or no apparent progress
- Significant materials awaiting installation
- Areas inaccessible for observation
- Visible construction deficiencies
- Apparent deviations from available plans or project information
- Damage to recently completed work
- Construction concealed before it could be observed
- Site conditions that may affect continued progress
A draw inspector documents these conditions objectively. The purpose is not to manage the contractor or direct construction. It is to give the lender a clearer understanding of observable conditions when evaluating the requested release of funds.
When progress or workmanship later becomes the subject of a dispute, that same objective record often becomes the starting point.
What a Construction Draw Inspection Does Not Do
A typical construction loan draw inspection is a visual assessment of observable construction progress. It is generally not:
- A code compliance inspection
- A municipal inspection
- A comprehensive quality-control inspection
- A guarantee of workmanship
- An engineering certification, unless performed within an engineering scope
- A verification of concealed construction
- A contractor payment authorization
- A guarantee that construction complies with every drawing or specification
- A replacement for architect, engineer, municipal, or other professional inspections
The inspector reports observable conditions and progress based on the information available at the time of the site visit. Decisions regarding the release of construction funds remain with the lender.
Why Documentation Builds Value Over Time
Construction changes quickly. Walls are closed, mechanical systems are concealed, and finishes cover what was visible a month earlier. A well-documented inspection captures the project at a specific point in time.
A single inspection describes current conditions. Recurring inspections build a progression history:
- Draw Inspection #1: Structural framing underway.
- Draw Inspection #2: Framing substantially complete; mechanical rough-ins underway.
- Draw Inspection #3: MEP rough-ins progressing; drywall beginning.
- Draw Inspection #4: Drywall substantially complete; finishes and equipment installation underway.
- Draw Inspection #5: Interior finishes approaching completion; final connections and commissioning remain.
This history lets the lender compare current conditions with prior observations and judge whether the project is moving forward consistently. It also makes unexplained jumps in reported progress easier to spot.
For a lender managing several construction loans, a dated photo record provides far more context than percentages on a spreadsheet.
Each piece of the draw package answers a different question:
- The draw request says what is being requested.
- The schedule of values shows how project costs are allocated.
- The construction schedule shows where the project is expected to be.
- The construction loan draw inspection shows what is actually observable at the property.
The inspection does not replace the contractor, architect, engineer, or the lender’s construction department. It adds an independent layer of documentation between the requested draw and observable progress.
Construction Loan Draw Inspection FAQ
How often are draw inspections performed? Most lenders order an inspection with each draw request, which is typically monthly. Smaller projects may be inspected at defined milestones instead.
Who orders the draw inspection? The lender usually engages the inspector directly to preserve independence. The cost is often passed through to the borrower under the loan agreement.
What does the lender receive? A written report covering observed progress by component, photographs, reported versus observable progress, stored materials when applicable, significant outstanding work, and any conditions that warrant attention.
Is a draw inspection the same as a Property Condition Assessment? No. A draw inspection tracks progress on a project under construction. A Property Condition Assessment under ASTM E2018 evaluates the condition of an existing building, typically for an acquisition or refinance.
Construction Loan Draw Inspections in New Jersey, Pennsylvania and the Philadelphia Region
Core Building Inspections provides Construction Loan Draw Inspections and Construction Progress Assessments for lenders, financial institutions, developers, and other commercial real estate stakeholders. We work throughout South Jersey and the Route 1 corridor, Philadelphia and its Pennsylvania suburbs, Delaware, and surrounding Mid-Atlantic markets.
Inspections can be performed as individual assignments or on a recurring basis throughout construction. Reports can include current construction status, photographic documentation, reported versus observable progress, significant outstanding work, stored materials, and other project-specific information the lender requires.
For lenders managing an active construction loan, independent field observations provide valuable context before additional project funds are released.
Core Building Inspections Commercial Property Due Diligence & Construction Progress Assessments NJ License No. 24GI00245900 · CCPIA Certified No. CCPIA-003719 609.605.0590 · info@corecreinspections.com · www.corecreinspections.com